Last updated: 2026-09-15
End of 2026, part D — Stablecoins, tokenized finance, agentic commerce
❓ What money rails are live in September 2026, and what is still a 2030 slide?
Secondary focus. Agentic commerce is treated as adjacent settlement and checkout context, not a protocol encyclopedia.
Live charts:
- USD stablecoin supply: stables.cool/USD
- Aggregate stablecoin market cap: defillama.com/stablecoins
- MacroMicro world stablecoin cap: en.macromicro.me/charts/134292/world-stablecoin-market-cap
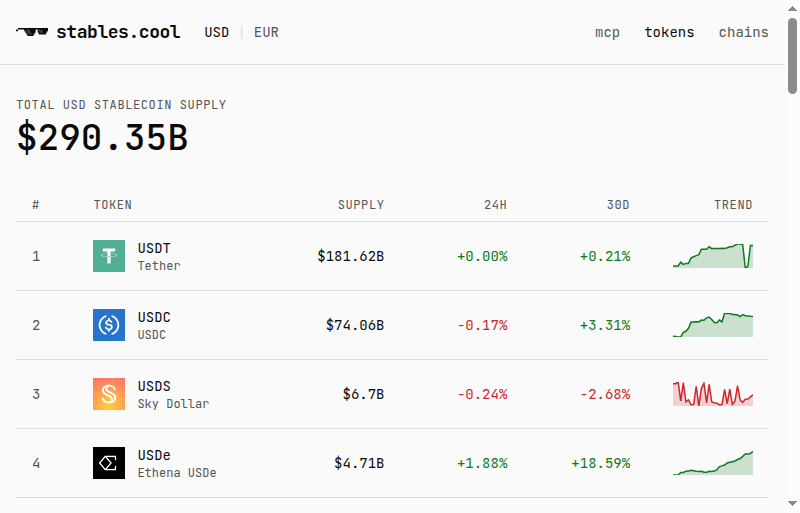
HAPPENED as a chart capture (15 Sep 2026): stables.cool printed $290.35B USD stablecoin supply (USDT $181.62B, USDC $74.06B). DefiLlama’s broader total the same day was ~$305B. Keep the band, not one dashboard.
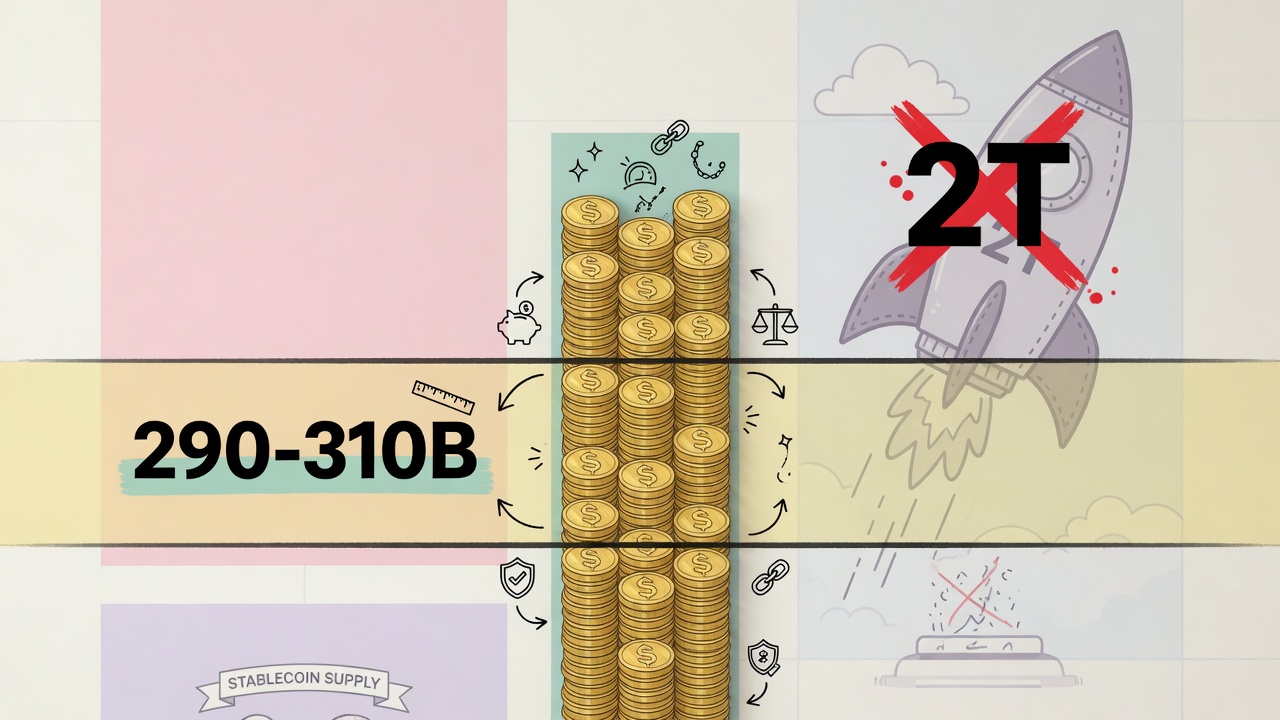
Stablecoin supply: a $290–310 billion band, not a $2 trillion year
❓ How much dollar-like crypto actually exists today, and why do dashboards disagree?
HAPPENED, 15 September 2026, same day, three printers:
| Dashboard | Notes | |
|---|---|---|
| stables.cool USD | $290.35B USD-pegged; USDT $181.62B, USDC $74.06B | USD-only lens; this package’s capture |
| StableCoin.com | $291.4B; USDT 62.9%, USDC 25.4% | Top-2 dominance 88.4% |
| DefiLlama | $305.3B total stables; USDT $183.3B, USDC $74.4B, USDT dominance 60.05%; 30d +1.56% | Includes more instruments (e.g. BUIDL, USYC listed on the same table) |
| MacroMicro | $310.06B | “World” series |
Do not flatten these into one number. DefiLlama is broader (yield-bearing and tokenized-dollar cousins sit on the same page). stables.cool is USD-pegged payment coins. A reader who says “stablecoins are $310B” and a reader who says “$290B” can both be looking at 15 September.
MEASURED TREND: logistic / plateau after a 2025 climb, not a 2026 melt-up. CoinGecko’s 2026 RWA report: stablecoin cap from $199.77B on 1 Jan 2025 to $301.65B on 31 Mar 2026 (+51%), with most of the growth Jan–Sep 2025, then a band around $290–300B. CoinDesk Research: a $320B ATH in May 2026. Stablecoin Beat: $303.11B end-June, −2.12% on the month. Andersen Institute (8 Sep 2026): dollar-pegged ~$300B as of August, of which reserve-backed ~$270B.
Classification: 2023–2025 looked exponential-ish off a low base. From late 2025 through mid-September 2026 the series is flat to slightly choppy. Calling end-2026 “the year stablecoins doubled again” would be a PREDICTION fighting the print.
USDT remains the volume horse (~73% of CEX stablecoin volume in CoinDesk’s May note) even as its share of cap slipped from ~69% (start-2025) toward ~60–63%.
GENIUS is law. End-2026 is not the effective date.
❓ What has the United States actually bound, versus what still needs rules and bank plumbing?
HAPPENED. The GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins) was signed 18 July 2025. It defines USD payment stablecoins: 1:1 high-quality liquid reserves, attestations, AML/CFT, no automatic deposit insurance, no automatic Fed master account, and a ban on issuers paying interest for merely holding the coin. Implementing rules were directed on an 18-month clock. Brookings (19 Aug 2026) cites USDT ~$190B and USDC ~$80B in its then-current snapshot, OCC conditional national trust-bank approvals for Circle, Paxos, Ripple and others in Dec 2025 and early 2026, and ~$1.2T/month of adjusted stablecoin transaction volume at year-end 2025. (Brookings)
PREDICTION / clock: Full framework effectiveness is widely cited as 18 January 2027. September 2026 X commentary says some 2026 rulemaking deadlines slipped. Treat “GENIUS is live as a complete bank-integrated regime” as a 2027 claim unless a final rule is published and linked.
Stablecoin Beat end-June: GENIUS-compliant supply $76.41B (25%); MiCA-compliant $74.28B (24%), with heavy overlap. Most of the float is still outside both stamps.
Andersen Institute: of $269.4B reserve-backed on 28 July 2026, 47.8% sat at CEX + DeFi venues (the intermediated share), up from 42.8% average in 2023 — evidence that a rising slice is used inside crypto, not as a new retail payment system. Cross-border payment share remains tiny in that literature (<0.2% in some 2026 notes).
Canadian fact, not a US fact: OSFI’s 10 September 2026 quarterly said tokenized deposits are not legally distinct from deposits, and B-13 / B-10 still apply. That is HAPPENED supervisory speech in Canada. It is not GENIUS.
Tokenized finance: Treasuries are the boring giant
❓ What has actually been put on-chain besides dollars?
HAPPENED, with a definition fight:
- CoinGecko (through 31 Mar 2026): tokenized RWAs $19.32B, of which Treasuries $12.99B (67% share), up from $5.42B at start-2025.
- CoinDesk Research (May 2026): tokenized assets $28.9B ATH, tenth consecutive monthly high; Treasuries ~$16.1–16.2B; tokenized stocks $2.41B; BlackRock BUIDL overtook Circle USYC as largest tokenized fund at $2.98B.
- CryptoBriefing (11 Sep 2026), citing RWA.xyz / NullTX: on-chain RWA $46.2B, US T-bills ~$15B, Ethereum ~$17.3B of distributed RWA; other trackers $38–46B depending on what counts.
Classification: Selective Institutional Tokenization Growth — stepwise, concentrated in cash-equivalents and Treasuries, not an exponential migration of all securities. The knowledge graph already holds this take.
Different from stablecoins: A payment stablecoin is a dollar-like bearer instrument with a reserve. A tokenized T-bill is a fund share. A tokenized deposit is a bank liability on a chain. Brookings’ August 2026 piece is the clean split.
Agentic commerce: protocols live, volumes not
❓ Have machines started paying, or have networks started writing PDFs?
HAPPENED (infrastructure, 2025–2026):
- OpenAI/Stripe Agentic Commerce Protocol (ACP) — ChatGPT Instant Checkout path.
- Google Universal Commerce Protocol (UCP) / AP2 — merchant discovery-to-order; Ulta Beauty cited as a late-April 2026 production merchant in industry round-ups.
- Visa Trusted Agent Protocol + Intelligent Commerce; Mastercard Agent Pay, Agentic Tokens, Payment Passkeys; Ant International Agentic Mobile Protocol.
- 10 September 2026: Visa, Mastercard, and Ant International announced work on a shared Know-Your-Agent framework (identity, permissions, continuous monitoring). That is an announcement of joint work, not a live global ID. McKinsey’s $3–5T of consumer commerce orchestrated by AI agents by 2030, cited in that announcement, is a PREDICTION. (The Next Web / Reuters / CNBC)
- Mastercard Europe: first end-to-end AI-agent payment claimed March 2026. Anthropic Project Deal: on the order of $4,000+ of agent-on-agent volume in a small experiment — the honest production-scale number in mid-2026 round-ups. (Major Matters)
PREDICTION (do not put in the 2026 happened column): Juniper $1.5T agentic commerce volume by 2030; eMarketer $144B US e-commerce from AI platforms by 2030; Mastercard “by 2027 agents negotiate price at scale.”
Gap that is HAPPENED as a gap: dispute, liability, and Europe’s SCA/PSD3 treatment of non-human initiators remain unresolved in the sources used here. Several protocol families, zero convergence on commitment governance, was the June 2026 stack-report finding.
x402 (HTTP 402 machine payments) is the best-fit metered API / content rail, often stablecoin-settled; it is not a retail dispute framework. Card-network agent tokens are the opposite: issuer-grade risk, closed ecosystems.
Hard-to-vary test: You cannot replace “$4,000 of experimental agent-on-agent flow” with “$1.5 trillion” and keep an explanation of 2026. The mechanism that exists is tokenized credentials + checkout APIs + incomplete identity. The mechanism that does not exist is universal machine legal personality with chargebacks.